Can your takeaway pay its way?
A takeaway can be busy and still fail to pay its way. Test whether each order leaves enough money to support the shop. Then check whether the kitchen can serve enough orders when customers want them.
This guide is SmallBizSim's own summary of public information and does not constitute business, financial, legal or tax advice.
Localise this guide
Choose your country
Demand
Start with a meal occasion
“Workers and families” is too broad to guide a menu or trading schedule. Define the purchase you want to win: lunch collected during a short break, dinner ordered on the journey home, or delivery for people who cannot collect. These are occasions to investigate, not established demand for your shop.
Ask what those customers currently buy, what they pay including delivery, and why they would switch. Your competition includes any practical substitute for that meal—not only shops serving the same cuisine.
Demand must also pay its way. An order may leave little after ingredients, packaging and channel fees, yet occupy the kitchen when better-contributing orders need it. Test both what orders leave and whether you can serve enough at the right times.
Move from background research to a small, permitted paid test:
Paid test records
Interviews explain preferences; paid repeat purchases test behaviour. A small trial cannot establish a full shop's sales. Compare the observed trading pattern with the costs and capacity of the operation you intend to open.
Money
Know what an order leaves
Keep the revenue basis consistent, including how applicable sales taxes are treated. Compare channels separately before combining them.
| Channel | Revenue to record | Order-linked costs to identify |
|---|---|---|
| Counter or direct collection | Realised food and drink sales, reflecting discounts and refunds | Ingredients, packaging, payment charges and other costs that vary with these orders |
| Your own delivery | Realised sales and any delivery charge retained by the shop | The collection costs above, plus delivery costs that vary with orders under your delivery arrangement |
| Third-party platform | Realised sales on a consistent basis—not simply the headline app order total | Ingredients, packaging, platform and payment charges, shop-funded promotions, refunds and other applicable fulfilment costs |
New Zealand government finance guidance explains contribution for an individual income stream.2 Canada's BDC identifies commissions, card fees, packaging and distribution as possible variable costs.3 Neither supplies typical takeaway channel margins or platform fee rates.
Menu mix matters too. Sides and drinks change the average basket; preparation speed changes capacity. Cost the basket, then test the work required to produce it. A cost list alone does not establish either contribution or capacity.
Break-even
Connect contribution, staffing and required orders
The U.S. Small Business Administration's basic break-even relationship is:4
For a takeaway with several channels, a practical planning extension is:
The weighted average uses each channel's contribution and its assumed share of orders. The staffing schedule helps set committed costs. Divide those costs by weighted contribution, then check whether the required orders fit peak capacity. If the mix shifts toward a lower-contributing channel while commitments stay unchanged, more orders are needed to cover them.
Build the calculation in this order:
- Choose one period and currency. Match the cost period to the order period. Include bills that arrive annually or quarterly.
- Set the staffing schedule. Establish who covers preparation, service, handoff, cleaning and management at the volume being tested.
- Separate committed and variable costs. Rent and minimum scheduled payroll are commitments for that scenario. Genuinely order-linked labour belongs in variable costs instead. Do not count the same wages in both places.
- Include the owner's work once. If you will work shifts, include an explicit allowance for that work. If someone else will do it, use their locally costed coverage. Do not add it again if already included in payroll.
- Calculate channel contribution and the assumed mix. Use the formula above to establish the order requirement.
- Rebuild the case when staffing changes. Extra shifts, overtime or another worker added beyond a volume threshold change the cost structure. The earlier order requirement no longer describes the same operation.
The SBA recognises that costs can be partly fixed and partly variable, including overtime above a production level.5 “Wages as a percentage of sales” is not a substitute for a workable roster. Use the full local employment cost, not only the advertised wage.
Applies to United Kingdom
In the United Kingdom, government business guidance identifies employer costs beyond salary, including National Insurance, pension contributions, leave and other employment expenses.6 These are UK employment obligations, not costs to copy into another jurisdiction's budget.
Capacity
Make the order target fit the meal peaks
A monthly calculation can conceal an impossible dinner rush. Customers need not arrive evenly across opening hours.
Allocate required orders across trading days and busy intervals using the demand pattern you have observed or are explicitly testing. Compare those requirements with accurate orders completed and handed off, not just orders accepted.
Run a service trial with the intended menu, staffing and channel mix. Follow each order through preparation, cooking, assembly, packing and handoff. Record where work accumulates and whether waiting orders interfere with incoming ones. A bottleneck at any stage limits completed orders, even when another station has spare capacity.
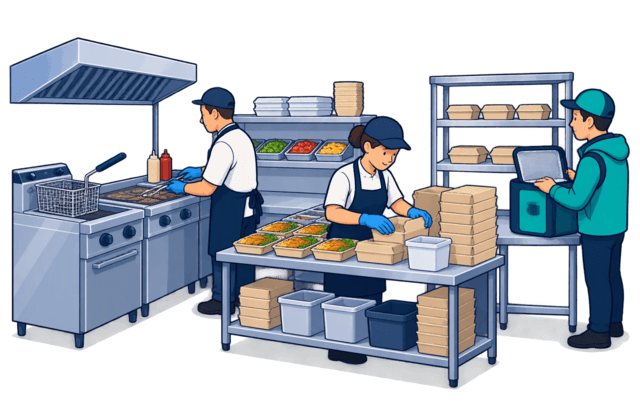
- A spare fryer does not solve a packing bottleneck.
- Another cook does not necessarily solve an obstructed collection area.
- Adding a dish can create a new preparation task even when its ingredients look inexpensive.
Test travel quality over the journey and waiting time customers are likely to experience. Packaging, texture, temperature and order accuracy are part of the offer.
Entry routes
Choose an entry route that fits your role
Starting independently, buying a shop and franchising bring different things to test.7 For any route, establish what you will do yourself and what others must cover.
Starting independently
You control the offer, but must build the customer base and operating routines.
Buying a shop
Trading history, staff and equipment may have value; check what survives the transfer.
Franchise
Brand support and systems come with fees and operating constraints.
A smaller trading format can test some assumptions before a full premises commitment. It still needs permissions suited to its location and food activity.
Applies to Australia
In Australia, home-based food businesses are not exempt from food-safety requirements simply because they are small or operate infrequently.8
Buyers: verify earnings and the work behind them
Treat a seller's profit summary as a claim to investigate. Ask an independent accountant to compare the accounts with underlying records for matching periods.9 Check seasonal patterns, not just a strong month.
Records to compare for matching periods
Document every proposed “add-back”—an expense the seller says can be removed when assessing earnings. Unsupported cash-sales claims and undocumented adjustments remain unverified.
Removing an owner's pay from the accounts does not remove their work from the kitchen. Identify what the seller and family members do, how they are paid, and what replacement coverage would cost under your plan. Distinguish earnings you can draw from compensation for shifts you must work.
New Zealand's government buyer guidance recommends checking key staff and whether customer or supplier loyalty depends on the current owner.10 Review those dependencies alongside equipment condition, supplier arrangements, the lease and permits relevant to the transfer.
Applies to United Kingdom
Part-time owners: name who covers your absence
“Staff will run it” is not a staffing plan. Specify who opens, supervises meal peaks, orders supplies, handles shortages, closes and covers absences. Price that arrangement before assessing what the business can pay you.
If your proposed manager or shift lead cannot cover the seller's role, you are assessing a different business from the one shown in the seller's accounts.
Rules
Check permissions for the actual address
Food-business registration or notification is only one part of opening. Give the responsible authority your address, menu, preparation methods and trading format before committing to premises or equipment. Ask which food, premises and activity-specific permissions apply.
These are starting points, not complete approval lists. Guidance and fee information were checked in October 2026.
Food-business starting points
AU Australia
Food-business starting point: Notify the relevant local food regulatory agency before food-handling operations commence.13 Use the Australian Business Licence and Information Service through business.gov.au to investigate activity-, state/territory- and council-specific permits.14
Cost evidence and its limits: No single national takeaway permit price is established here. Confirm fees and conditions with the issuing authorities.
NZ New Zealand
Food-business starting point: Determine the applicable Food Control Plan or National Programme, register with the council or MPI as directed, and arrange verification. Many single-council-area template-plan food-service businesses register with their council.15
Cost evidence and its limits: The 2026–27 Food Business Levy is NZ$86.25 excluding GST per year: per registered place for Food Control Plans and per business for National Programmes. Council collection charges may apply; specified mobile or market operations can qualify for a partial waiver.16 Registration and verification costs are separate.
CA Canada
Food-business starting point: Use BizPaL for participating jurisdictions and confirm provincial/territorial and municipal food-premises requirements.17 CFIA federal licensing requirements depend on activities such as importing or preparing food for export or interprovincial trade; some federal requirements can also apply within one province.18
Cost evidence and its limits: No comparable national takeaway fee is established here. Do not assume that every local shop needs a federal Safe Food for Canadians licence—or that federal rules can always be ignored.
GB United Kingdom
Food-business starting point: GOV.UK guidance says new or taken-over food businesses must register with the local authority at least 28 days before trading.19 Consult the relevant local and devolved food authority.
Cost evidence and its limits: Food-business registration is free (£0). That does not make premises work or other approvals free.
US United States
Food-business starting point: Check the state, local, tribal or territorial authority responsible for the site. The FDA Food Code is a model for adoption, not a single nationwide restaurant permit.20
Cost evidence and its limits: Requirements and fees vary by activity and location.21 Obtain the actual permit schedule rather than using a national allowance.
Cash
Keep a separate cash plan
Covering operating costs does not mean you have enough cash to open or continue trading. Deposits, fit-out payments, equipment, opening stock and financing outflows have their own timing. Annual bills and settlement delays can create pressure that a monthly operating average hides.
Prepare a cash schedule showing when payments leave and receipts arrive. Include the owner's cash needs consistently with the staffing and compensation assumptions already used.
Before committing, bring together four pieces of evidence:
Evidence before committing
Resolve weak evidence before increasing the commitment. More orders help only when the shop can fulfil them and retain enough to support the operation.
Summary
Key takeaways
- Define the meal occasion you want to win, then test it with paid trading through ordinary periods.
- Average order value and contribution per order are different measures; compare channels separately before combining them.
- Required orders depend on committed costs, including a workable roster and the owner's work counted once, and on weighted contribution per order.
- A monthly order target must also fit the meal peaks your kitchen can complete and hand off.
- Buyers should verify earnings and the work behind them; part-time owners need named coverage.
- Confirm permissions for the actual address, and keep a separate cash plan.
Sources
- Market research and competitive analysis — U.S. Small Business Administration
- Key equations for your finances — Business.govt.nz
- What are variable costs? — Business Development Bank of Canada
- Break-even point — U.S. Small Business Administration
- Break-even calculator guidance — U.S. Small Business Administration
- Understanding the costs of employment — Business.gov.uk
- Buy an existing business or franchise — U.S. Small Business Administration
- Home-based food businesses — Food Standards Australia New Zealand
- Financial Due Diligence for Acquisition — Eger CPA, June 2026
- Buying a business or franchise — Business.govt.nz
- Transfers of employment contracts — GOV.UK
- Surviving as a Chinese takeaway shop during the Coronavirus outbreak — SBS Voices, 2020 (updated 2021)
- Starting or changing a food business — Food Standards Australia New Zealand
- Register licences and permits — Australian Government
- Register a food business under the Food Act — NZ Ministry for Primary Industries
- Food Act 2014 fees, charges, and levies — NZ Ministry for Primary Industries
- BizPaL Initiative — Innovation, Science and Economic Development Canada
- Starting or expanding a food business? — Canadian Food Inspection Agency
- Starting a food business — GOV.UK
- Food Code 2026 — U.S. Food and Drug Administration
- Apply for licenses and permits — U.S. Small Business Administration