33-42%
Cost of sales as a share of annual turnover across the ATO's three coffee-shop turnover bands (34-42%, 35-41% and 33-38%), 2023-24 tax returns. Excludes coffee carts and vans.
Choose the customer visit your cafe will serve. Then check whether enough complete orders can pay for staff, premises and your own work.
This guide is SmallBizSim's own summary of public information and does not constitute business, financial, legal or tax advice.
Localise this guide
At a glance
Figures to check for your country
33-42%
Cost of sales as a share of annual turnover across the ATO's three coffee-shop turnover bands (34-42%, 35-41% and 33-38%), 2023-24 tax returns. Excludes coffee carts and vans.
12%
General super guarantee rate on eligible employees' qualifying earnings, paid each payday from 1 July 2026.
NZ$60,000
Taxable-activity turnover at or above which GST registration is required, over the last or next 12 months.
1.5x
Minimum pay for time worked on a public holiday, plus an alternative paid holiday if it is an otherwise working day.
C$30,000
GST/HST small-supplier threshold for most businesses, tested in one calendar quarter or over four consecutive quarters.
£90,000
VAT registration threshold: taxable turnover over the last 12 months, or expected in the next 30 days alone.
28 days
Minimum notice to register a new or taken-over food business before trading in England, Wales and Northern Ireland.
US$15.00/hr
2025 national median wage for fast food and counter workers, the group that includes baristas.
Demand
Customers buy more than a drink: a quick stop, breakfast they did not have to cook, somewhere to meet, or a familiar conversation. That reason affects when they arrive, how long they stay and what they order.
A takeaway coffee bar and a sit-down brunch cafe can sell the same drink while being very different businesses. One needs to serve customers before they leave for work. The other must coordinate tables, cooking and washing up.
Premises, staffing and cash needs follow from that choice. Promising every kind of visit from a space or roster designed for only one is difficult.
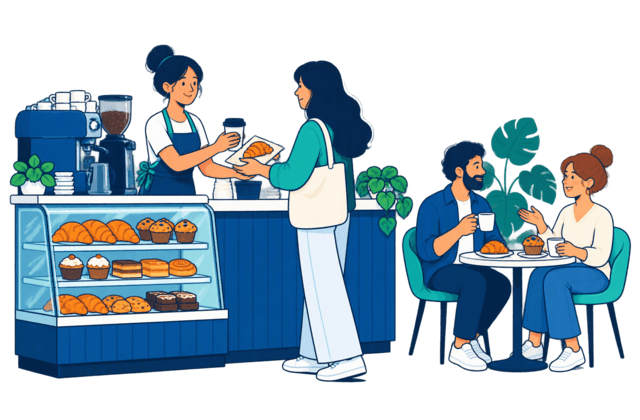
Three different cafe visits
What brings someone back: convenient access, a dependable drink and a predictable wait.
What you have to make work: enough completed orders during a short rush, and an easy way to order, pay and collect.
What brings someone back: a comfortable place, recognition and food worth returning for.
What you have to make work: enough spending across the time seats are occupied, without making hospitality feel like a countdown.
What brings someone back: food and an experience worth a deliberate trip.
What you have to make work: kitchen preparation, table service and cleaning, including on quieter trading days.
These visits can overlap. A lingering table is not a problem by itself; it becomes one if the plan depends on repeatedly selling that same seat.
A loyal customer need not be a daily customer. Watch the occasions you intend to serve at a prospective site. Record the time, weather, nearby activity, people passing, customers entering and orders being collected. Keep those observations separate.
An appropriately permitted market stall, pop-up or other small paid test can reveal more than a positive answer to "Would you come here?" Record what people buy at the intended prices and whether they buy again.
Money
The money left after coffee beans and milk is not the owner's income. Cups, food, waste, payment fees, staffing and premises still have to be paid for.
Start with sales after discounts and refunds, keeping taxes collected for government separate where applicable. Then distinguish three questions.
Gross profit is sales less the cost of goods sold. For a cafe, that includes ingredients and bought-in food consumed in making those sales, including waste. Stock bought this week is not necessarily stock used this week. Check how packaging is classified, and keep that treatment consistent.
Deduct costs that arise with that order, such as ingredients, packaging and transaction charges. The amount left helps pay for the roster, rent and other commitments. It is not net profit. If extra orders require another person or a longer shift, that labour has to be covered too.
Allow for paid labour, premises, utilities, insurance, software, maintenance and other operating costs. A full profit assessment must also deal with depreciation, financing and tax as appropriate. Keep the owner's work visible rather than letting unpaid shifts make the result look stronger.
For a realistic mix of complete orders, work out the average amount left per order after ingredients, waste, packaging and transaction costs. Include discounts and any delivery fees.
For the same planning period, list what those orders must cover: the workable roster, premises and other recurring commitments. Include a realistic allowance for your work, counted once if it is already in payroll. Do not include costs already deducted per order in this second total.
Dividing those commitments by the average amount left per order gives the order volume needed to cover them. A zero or negative amount left cannot cover positive commitments through more orders.
Spread the required orders across the days and hours you will actually trade. Check the busiest window against both demand evidence and the complete orders the team can finish. A daily total that depends on an impossible morning queue is not workable. If the volume needs another worker or longer shifts, increase the roster cost and test again.
Try it
Interactive estimate
Use one period throughout, such as a week or a month, and your own currency. There are no default values.
Enter your own numbers to see how many complete orders they imply. Nothing is pre-filled: use your own prices, quotes and roster.
Your country
Build the plan in the currency of the place where you will trade. Converting an overseas coffee price does not reproduce its tax treatment, wage bill or customer demand.
Country rules and costs
AU Australia
Currency: AUD. Australia's tax office publishes coffee-shop benchmarks from 2023-24 Australian business tax returns.1 They cover businesses selling coffee, tea, other drinks and food, not coffee carts, vans or other mobile retailers.
| Category | Low end of range | High end of range |
|---|---|---|
| AUD 65,000-250,000 turnover | 34 | 42 |
| AUD 250,001-600,000 turnover | 35 | 41 |
| More than AUD 600,000 turnover | 33 | 38 |
ATO benchmark ranges for Australian businesses selling coffee, tea, other drinks and food; excludes coffee carts, vans and other mobile retailers.
Reported expense ranges are percentages of annual turnover; turnover bands are in AUD.
| Annual turnover, AUD | Cost of sales | Labour | Rent | Total expenses |
|---|---|---|---|---|
| $65,000-$250,000 | 34-42% | 21-32% | 10-17% | 73-86% |
| $250,001-$600,000 | 35-41% | 21-32% | 8-14% | 81-90% |
| More than $600,000 | 33-38% | 27-35% | 6-10% | 86-93% |
Employment costs extend beyond the hourly wage. The ATO's general super guarantee rate is 12% in 2026-27, applied to eligible employees' qualifying earnings under Payday Super.2 From 1 July 2026, contributions follow each payday rather than the former quarterly cycle. Budget super with each pay run.
NZ New Zealand
Currency: NZD. Employment New Zealand says employees working on a public holiday must receive at least time and a half for the time worked.4 An alternative paid holiday is also due when it is an otherwise working day, except for employees employed only to work on public holidays. Include the wage entitlement and any future cover for the alternative holiday when deciding your hours.
Inland Revenue generally requires GST registration when taxable-activity turnover was at least NZ$60,000 in the last 12 months, or is expected to be at least that amount in the next 12 months.3 Adding GST to your prices also requires registration. Test prices and cash with the correct registration status, rather than treating collected GST as spending money.
CA Canada
Currency: CAD. For most businesses, the CRA's C$30,000 threshold can be exceeded in a single calendar quarter or over four consecutive calendar quarters, and the timing of registration and charging differs.5 Exceeding it in one quarter makes the very sale that crosses the threshold taxable.
A bag of coffee beans and a prepared hot drink need not have the same tax treatment. CRA guidance lists coffee beans among zero-rated basic groceries, while food and beverages heated for consumption are excluded from that zero-rating.10 For taxable supplies, the GST/HST rate depends on the province or territory of supply; provincial sales-tax obligations may also need checking.11
GB United Kingdom
Currency: GBP. HMRC distinguishes food consumed on the premises from eligible cold takeaway food. Hot takeaway coffee is standard-rated; some cold takeaway food can be zero-rated.12
For a UK-established business, VAT registration is normally required if taxable turnover exceeds £90,000 over the last 12 months, or is expected to exceed that amount in the next 30 days alone.6 Zero-rated taxable sales still count.
Include employer National Insurance in the payroll assessment, with the applicable employee categories and reliefs, rather than stopping at the advertised hourly wage.13 For premises, the Food Standards Agency's guidance for England, Wales and Northern Ireland requires registration at least 28 days before trading, including a takeover.7 In Scotland, check with your local authority.
US United States
Currency: USD. Do not copy a low tipped cash wage into a barista budget without checking the role and location. Under federal FLSA rules, a permitted tip credit has conditions; the employer must make up a shortfall if actual tips and direct wages do not meet the required federal minimum.14 Some states require higher cash wages or prohibit tip credits. Apply the more protective applicable standard, and check local requirements too.
For a sense of the labour market, the federal Bureau of Labor Statistics put the 2025 national median wage for fast food and counter workers, the group that includes baristas, at US$15.00 an hour.8
A tip jar is not cafe revenue to fund the rent. Federal rules prohibit employers, managers and supervisors from keeping employees' tips, with a limited exception for tips for service a manager directly and solely provides. Design any pool around the actual rules.
Operations
The espresso machine does not determine capacity on its own. After ordering and paying, customers may need both drinks and food. Those jobs must come together at handover: a fast drink can still wait for a toasted sandwich, blocking collection space.
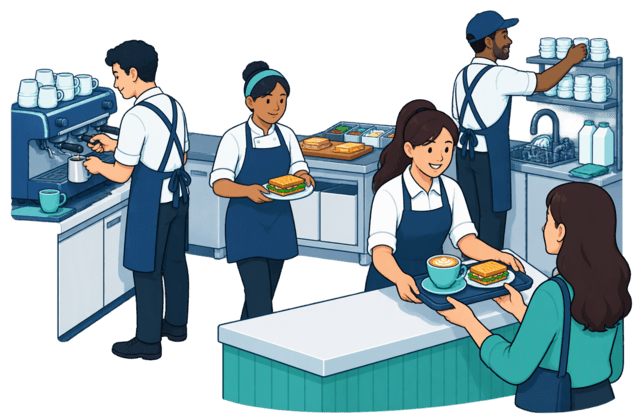
Restocking and washing up keep both drink and food preparation moving. Payment and food preparation may share a worker, so the limiting task depends on the menu, workspace and staffing.
Walk a realistic mix of orders through the proposed workspace. Include different drinks, food preparation, restocking and washing up, not just an uninterrupted run of identical coffees. Watch where work waits and where people cross each other's path.
Build the roster around those jobs, including work outside opening hours. Preparation, receiving deliveries and cleaning still need doing when nobody is buying. A quiet spell does not automatically remove a paid shift.
Ask who covers a break or an absence. If the answer is always the owner, show those hours in the plan. A manager-operated cafe needs paid management and cover, not the same roster with the owner's name removed.
Menu
A wider menu creates more reasons to visit, but also work before an order arrives. Bought-in pastries tie up cash and can remain unsold. Cooked dishes need preparation, storage, equipment and cleaning. An ingredient used in one slow-selling dish may still come in a supplier's minimum pack size.
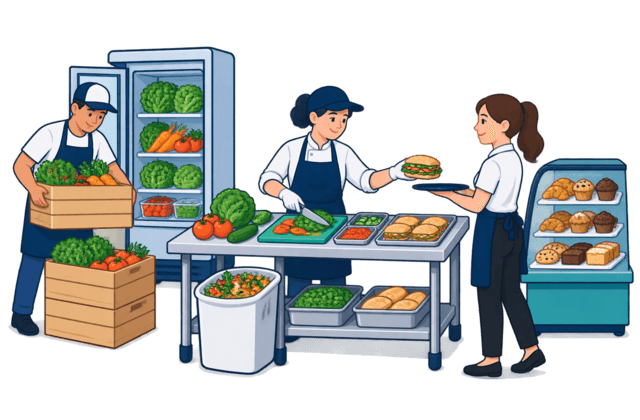
Follow each item's whole journey: delivery quantity, storage, preparation, portion size, service and unsold remainder. Compare the supplier's usable yield with what reaches the plate, not just the pack price. Shared ingredients or preparation may fit an existing shift; another item may require a new station or earlier start.
Price changes also need a customer response, not just a cost calculation.
After a price change, watch order numbers, product mix and spending together. A higher price is not a complete answer if visits or food purchases fall.
Owner pay and cash
An owner can receive pay for working in the cafe and a return for putting capital at risk. They are different rewards.
List your jobs: opening, service, ordering, recruitment, bookkeeping and covering gaps. Allow a realistic local cost for that work. If an appropriate owner salary is already in payroll, count it once. If you take drawings rather than a salary, ask your accountant to distinguish those withdrawals from business expenses.
Judge what is left after allowing for the work. A cafe that supports an owner-operated job may be worthwhile. It is different from an investment that pays a manager and still produces a return without regular unpaid rescue shifts.
Cash in the bank is different again. Loan proceeds can increase the balance without creating profit. Repaying loan principal uses cash but is not an operating expense; interest is separate. Equipment can require cash now while its accounting cost is recognised over time. Money held for taxes or approaching supplier bills is not freely available to spend.
A fitted coffee bar with suitable services is not the same project as an empty unit needing drainage, electrical work and a kitchen. Build the budget for the actual premises and format.
Build a dated cash plan from written quotes and payment terms, showing committed funding as well as outgoings. Include household needs separately so neither budget relies on unexplained withdrawals from the other.
Routes in
What each route gives you, and what it leaves to prove
You gain: freedom to choose the offer, suppliers and operating approach.
Still to prove: demand at this site, the installed cost of the premises, and your ability to assemble and train the team.
You gain: a trading operation and records you can investigate.
Still to prove: whether reported earnings survive a change of owner, actual staffing costs, equipment condition and the lease arrangements.
You gain: access to a brand and operating system, with support defined by the agreement.
Still to prove: whether that support and demand justify all fees, supply conditions, required investment and limits on your decisions.
The routes overlap: an existing cafe can also be a franchise. Each still requires investigation of the site.
Check permitted use, required services and the proposed menu before committing to a fit-out. Establish who pays for changes, what approvals are needed and what happens if opening is delayed. Food-business registration alone is not enough.
Ask an accountant to reconcile point-of-sale reports with accounts, tax filings, banking and payment-processor settlements, allowing for cash, fees and timing differences. Review monthly and time-of-day trading, not just an annual total or the busiest weekend.
Check payroll and the seller's actual work. If a sales listing adds the owner's pay back to show "adjusted" earnings, some of that amount may be the cost of a job you must do or replace. Ask what each adjustment represents.
Inspect equipment ownership, service history and likely replacement needs. Check lease transfer or renewal, rent changes, outstanding obligations and what is included in the price. Establish what a handover provides and whether key staff will stay.
Establish what training, opening help and ongoing support are promised. Check approved suppliers, pricing freedom, required hours, refurbishment obligations, territory and terms for renewal, transfer or exit. If a royalty is charged on sales rather than profit, it can remain payable in a loss-making month.
Ask current and former franchisees about support and their actual workload, and have a lawyer and accountant review the agreement.
Decide
Choose a question you have not settled and use its yes/no options to find the next action.
Before you commit money
Record what you saw: passers-by, entries and collected orders, kept separate. Use it as demand evidence in your plan.
Observe the site at the hours you would trade, or run a small paid test, before signing for premises.
Use that amount to estimate the orders needed to cover your commitments.
Rework prices, menu or supplier terms first. More orders cannot cover commitments when each order leaves nothing.
Check the same roster can also cover preparation, cleaning, breaks and absences.
Change the workflow or add staff, then raise the roster cost and recalculate the orders needed.
Judge the investment on what is left after paying for that work.
Add an allowance for your hours, or a paid manager, before reading any result as a return.
Size the cash reserve to those timing gaps and keep household needs separate.
Collect written quotes and payment dates, then build the calendar before committing to a fit-out or purchase.
Build those costs and timings into the plan in your own currency.
Use your country panel and the relevant authority's current guidance, and take advice where the rules are unclear.
Compare what you would inherit or be bound by with the costs of opening independently.
Do not rely on adjusted earnings, a sales listing or franchise marketing until they have.
Self-check
Use this checklist to identify missing records, quotes and confirmations.
How much evidence have you gathered?
8 of 8 checks still need documented evidence. This is not a feasibility verdict.
Gather evidence next
Summary
Next steps
Make assumptions traceable: label sales estimates as trading records, paid tests, observations or untested beliefs. Link menu costs to portions, waste and supplier terms, and labour costs to the roster.
Test things that could go wrong together. Lower weekday demand may reduce stock use but leave the opening shift and rent unchanged. A slower kitchen may limit completed orders even with customers waiting. A delayed opening can consume cash without changing the eventual menu price.
Use these cases in a financial model to find commitments that depend on weak evidence. Then choose the next action: simplify the menu, investigate another site, run a paid test or decide not to buy.
FAQ
There is no single budget for every format and premises. Build yours from written quotes, payment dates and a reserve for delays or slow sales. See opening costs and cash timing.
Your pay for working and your investment return are different rewards. See how to allow for owner work before assessing what remains.
The orders-needed estimator works in complete orders. Check its result against demand and the team's rush capacity.
No. Passing traffic is not the same as purchases. See what to observe and test at the site.
Use the route comparison to separate what each option provides from what you still need to investigate.
It depends on your country, turnover and sometimes your pricing. Check the country notes for the applicable thresholds and treatment.
A permitted federal tip credit has conditions, and state or local rules may be more protective. The US notes explain wage shortfalls, tip ownership and the limited manager-service exception.
No, but a trial shift or paid test can reveal skills your plan still depends on proving. Start with complete-order workflow and roster cover.