Starting or buying a florist
A florist must deliver flowers on time, not just make them look good. Choose orders that pay for the work they require and fit your storage, staffing and delivery capacity.
This guide is SmallBizSim's own summary of public information and does not constitute business, financial, legal or tax advice.
Localise this guide
Choose your country
Offer
Choose your orders before choosing premises
Daily retail, recurring accounts and events make different demands on the same florist. Decide which will lead your offer rather than assuming a shop can serve every occasion equally well.
A gift arriving today, funeral flowers and a wedding installation each carry a deadline. Buying, conditioning, designing and delivering perishable materials must fit that promise—not just the time spent arranging them.
Pre-selling helps you see demand, but it does not create more hours on a busy Saturday. Check whether the orders you can win will pay for their work and fit the dates, storage and delivery capacity you have.
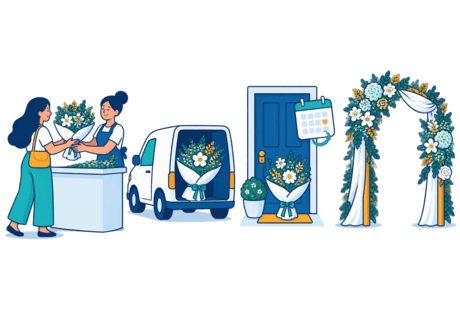
What each order type asks of the business
Everyday gifts and walk-in bouquets
What the customer is buying: A convenient, attractive choice available when needed.
What to establish: Which designs sell at paid prices, how much stock remains unsold, and how long each transaction takes.
Delivered gifts
What the customer is buying: The arrangement plus reliable arrival.
What to establish: Delivery windows, recipient arrangements, route time and the cost of failed delivery or replacement.
Subscriptions and business accounts
What the customer is buying: A repeat service with consistent presentation.
What to establish: Actual repeat orders, service expectations, payment terms and whether deliveries can be grouped.
Weddings and other planned events
What the customer is buying: Design, coordination and fulfilment on a fixed date.
What to establish: Consultation and revision work, final scope, supplier availability, setup access and competing bookings.
Funeral work
What the customer is buying: Appropriate flowers delivered to a sensitive deadline.
What to establish: Ordering details, communication responsibilities and a dependable handover to the receiving location.
A recognisable style helps customers choose you, but the service promise must be equally clear. “Seasonal bouquets for local collection” and “bespoke wedding installations” require different purchasing, staffing and customer communication.
Test an offer through paid orders before expanding it. Record the realised selling price, materials used, time spent, delivery work and whether the customer returns. Enquiries and compliments are leads, not completed sales.
Money
An order must pay for more than its flowers
Contribution is what an order leaves toward ongoing overhead and owner pay after its attributable costs. A high selling price tells you little if the order needs extensive consultation, expensive materials or a difficult delivery.
| Item | How to treat it when judging the order |
|---|---|
| Arrangement, vase and other items sold | Include their selling income, with a consistent treatment of applicable sales taxes |
| Delivery charge | Count the charge as income, then identify delivery expense separately; the fee is not automatically profit |
| Flowers, foliage and packaging | Record the materials consumed and account for unsold or discarded stock across the relevant purchasing batch |
| Paid work attributable to the order | Include preparation, design, packing, setup and delivery—not just arranging time |
| Payment, platform or order-service fees | Identify fees triggered by that sale |
| Customer deposit | Treat it as part payment toward the agreed order, not an additional sale on top of the full price |
Purchased stems and sold stems are not the same quantity. Stock may go into another order, remain usable, be discounted or be discarded. Track those outcomes by variety and purchasing batch. If you allocate a batch's waste cost across the orders it supplied, do not charge the same discarded stems again as a separate order expense.
Treat labour consistently, too. If employee wages sit in your ongoing payroll budget, do not deduct those same wages in full from individual orders and then subtract payroll again. Order-time records show which work consumes capacity and whether prices support the staffing needed to deliver it.
A positive order contribution is not the shop's final profit. Rent, refrigeration, utilities, insurance, software and other ongoing expenses still need covering, as does compensation for the owner. Ask an accountant to help keep management costing and formal accounts consistent, including how deposits and taxes are recorded.
Cash
Cash can leave before the flowers sell
A well-priced event can still require supplier payments before the customer's remaining balance arrives. A deposit improves cash timing, but money received for unfinished work is not automatically spare cash.
Keep a payment calendar alongside the order calendar. Show when supplier invoices, payroll, rent and other bills fall due, when customer balances are expected, and what work remains attached to money already collected.
Separate opening commitments from the cash needed to keep trading.
Getting ready to trade
Premises deposits, refrigeration and equipment are opening commitments.
Staying able to trade
Stock, wages and bills continue while demand develops.
Obtain local quotes in your operating currency. An overseas wage reference or equipment price is not a substitute for your own staffing plan or supplier quote.
Capacity
Check capacity before selling the date
A wedding booking reserves more than the event day. It uses consultation time, purchasing deadlines, conditioning space, preparation hours and transport. Bookings can compete for the same resources even when their ceremonies start at different times.
Before accepting another dated commitment, work backwards from the promised handover:
- Delivery and setup: Check access times, travel, unloading, installation, collection and who will be available for each task. Do not count one vehicle or person in two places at once.
- Design and packing: Place the work into the actual team's schedule, including existing retail and account orders. Written recipes and a production sequence make the required work easier to see.
- Processing and storage: Check when flowers arrive, who conditions them, and whether usable cooler and workspace capacity can hold incoming stems and finished designs together.
- Sourcing and cash: Confirm availability, substitution options, ordering deadlines and payment dates with suppliers.
- Remaining room: Leave a deliberate allowance for disruption and any walk-in or last-minute work you intend to serve. If you cannot accommodate it, narrow or close that part of the offer.
US retailers reported by the Society of American Florists have used narrower holiday ranges, ready-made arrangements, early-order offers and order cutoffs.4 These change when and how work arrives. Ready-made stock still occupies space and risks remaining unsold.
Buying
Check what survives the seller's departure
An established florist may bring customers, equipment and staff. Check how earnings would change after replacing the seller's work.
New Zealand's official business-buying guidance recommends checking financial trends, contracts, key staff and customer loyalty to the current owner.5 For a florist, examine what would remain after handover.
Records to request from the seller
Have an accountant assess the cost and capability needed to replace the seller's role. Distinguish repeat paid orders from enquiries, provisional bookings and one-off purchases. Establish which staff intend to stay and how important customer relationships will be handed over.
For each unfinished event, record the agreed scope, date, total price, payments received, remaining balance, changes, cancellation terms and remaining fulfilment cost. Reconcile receipts to bank and accounting records. A deposit may already have been spent while the flowers and labour are still to be funded.
Tax due diligence is a separate check. Australia's ATO warns that a share purchase may expose a buyer to the company's tax history.6 Canada's CRA addresses allocating the purchase price among assets, inventory and goodwill.7
Other ownership paths
Starting from scratch
Avoids relying on a seller's history, but means building your own orders and operating routines.
Franchise
Assess the actual fees, required suppliers, operating restrictions, support and exit terms. A brand does not remove the need to check demand and delivery capacity.
Your country
Check requirements for your location and activities
These official resources cover different parts of starting or buying a business. They are starting points, not a complete florist compliance checklist.
Official starting points and what still needs checking
AU Australia
Useful official starting point: business.gov.au says licence and permit needs depend on activities, state or territory and local government area, and directs businesses to ABLIS.8
What still needs a separate check: The chosen premises, trading activities, employment arrangements and tax position. Obtain local spending quotes in AUD.
NZ New Zealand
Useful official starting point: Business.govt.nz's buying guide covers financial, contract, staff and owner-loyalty checks.5
What still needs a separate check: Startup permissions, employment and tax requirements; legal responsibility for inherited bookings. Obtain local spending quotes in NZD.
CA Canada
Useful official starting point: Federal registration guidance asks founders to establish location, operating provinces or territories, name and business type;9 CRA provides purchase-accounting guidance.7
What still needs a separate check: Provincial, territorial and municipal requirements, staffing costs and customer-contract transfer. Obtain local spending quotes in CAD.
GB United Kingdom
Useful official starting point: GOV.UK's startup portal separates business structure, tax, employment, licences and home-business guidance.10
What still needs a separate check: Which rules apply to the premises and activities, and the actual employment and tax costs. Obtain local spending quotes in GBP.
US United States
Useful official starting point: The SBA explains business-purchase and franchise choices.11
What still needs a separate check: State and local registration, premises and employment requirements, applicable taxes and inherited customer obligations. Obtain local spending quotes in USD.
Before committing to premises, check whether your intended use—including home trading, collections or market selling—is allowed. If you plan to import flowers directly, investigate that activity separately rather than assuming a wholesaler's arrangements cover you.
Comparable florist startup budgets, waste rates and owner-income figures are not established here. Build your decision from local quotes and your own order records. Start with a small offer whose paid demand, labour, waste and delivery performance you can observe—or, for an acquisition, records that show what you are buying.
Summary
Key takeaways
- Decide which orders will lead your offer—daily retail, recurring accounts or events—before choosing premises.
- Judge an order by what it leaves after its attributable costs, not by its selling price. A positive contribution is still not the shop's final profit.
- Keep a payment calendar beside the order calendar. Cash received for unfinished work is not automatically spare money.
- A date is not available to sell until delivery, design, storage, sourcing and cash are all confirmed.
- When buying a shop, test what remains after the seller's work, relationships and obligations change hands.
Sources
- How I became a florist (Small Business UK; updated 20 July 2026; Alys of Blomst's subscription offer and working routine)
- A behind-the-scenes look at a florist on Valentine's Day (Lilygrass, US; undated; one US shop's advance buying, staffing and storage account)
- Valentine's Day interview with Avalon Florals (Wildflower Academy; undated; discusses Valentine's Day 2024 in Brisbane, Australia)
- Valentine's Day Prep: Best-Kept Secrets for Success (Society of American Florists; 24 January 2024; attributed US retailers' production, delivery and cutoff practices)
- Buying a business or franchise (Business.govt.nz; undated; New Zealand due-diligence guidance)
- Acquiring a new business (Australian Taxation Office; updated 31 May 2016; commercial and tax due diligence, including share-purchase tax-history risk)
- Buying an existing business (Canada Revenue Agency; undated; allocation of purchase price to assets, inventory and goodwill)
- Register licences and permits (business.gov.au; accessed 19 October 2026; Australia's activity- and location-specific permit guidance)
- Registering your business with the government (Canada.ca; modified 29 July 2024; federal registration starting points)
- Start your business (GOV.UK; accessed 19 October 2026; navigation to UK startup, tax, employment, licence and home-business guidance)
- Buying an existing business or franchise (US Small Business Administration; undated; general ownership-path trade-offs)